Bonds vs Gold vs Managed Futures: A 25-Year Perspective
Rethinking traditional asset allocation
October 2026. Reading Time: 10 Minutes. Author: Nicolas Rabener.
SUMMARY
- Gold would have diversified best over the last 25 years
- Bonds and managed futures provided similar diversification benefits
- Bonds are likely to become riskier going forward
INTRODUCTION
In our recent article, Bonds vs. Gold vs. Managed Futures: A 100-Year Perspective, we concluded that investors can replace U.S. government bonds and gold with managed futures. Given that the latter can allocate to either and capture trends in both fixed income and safe-haven assets like gold, this was perhaps not surprising.
However, the managed futures index we used was largely a backtest from AQR and did not reflect realized returns of funds. Backtested returns are typically overstated, which implies the analysis should be viewed with some skepticism.
Given this, we replicate the analysis over the last 25 years, where realized returns are available.
PERFORMANCE
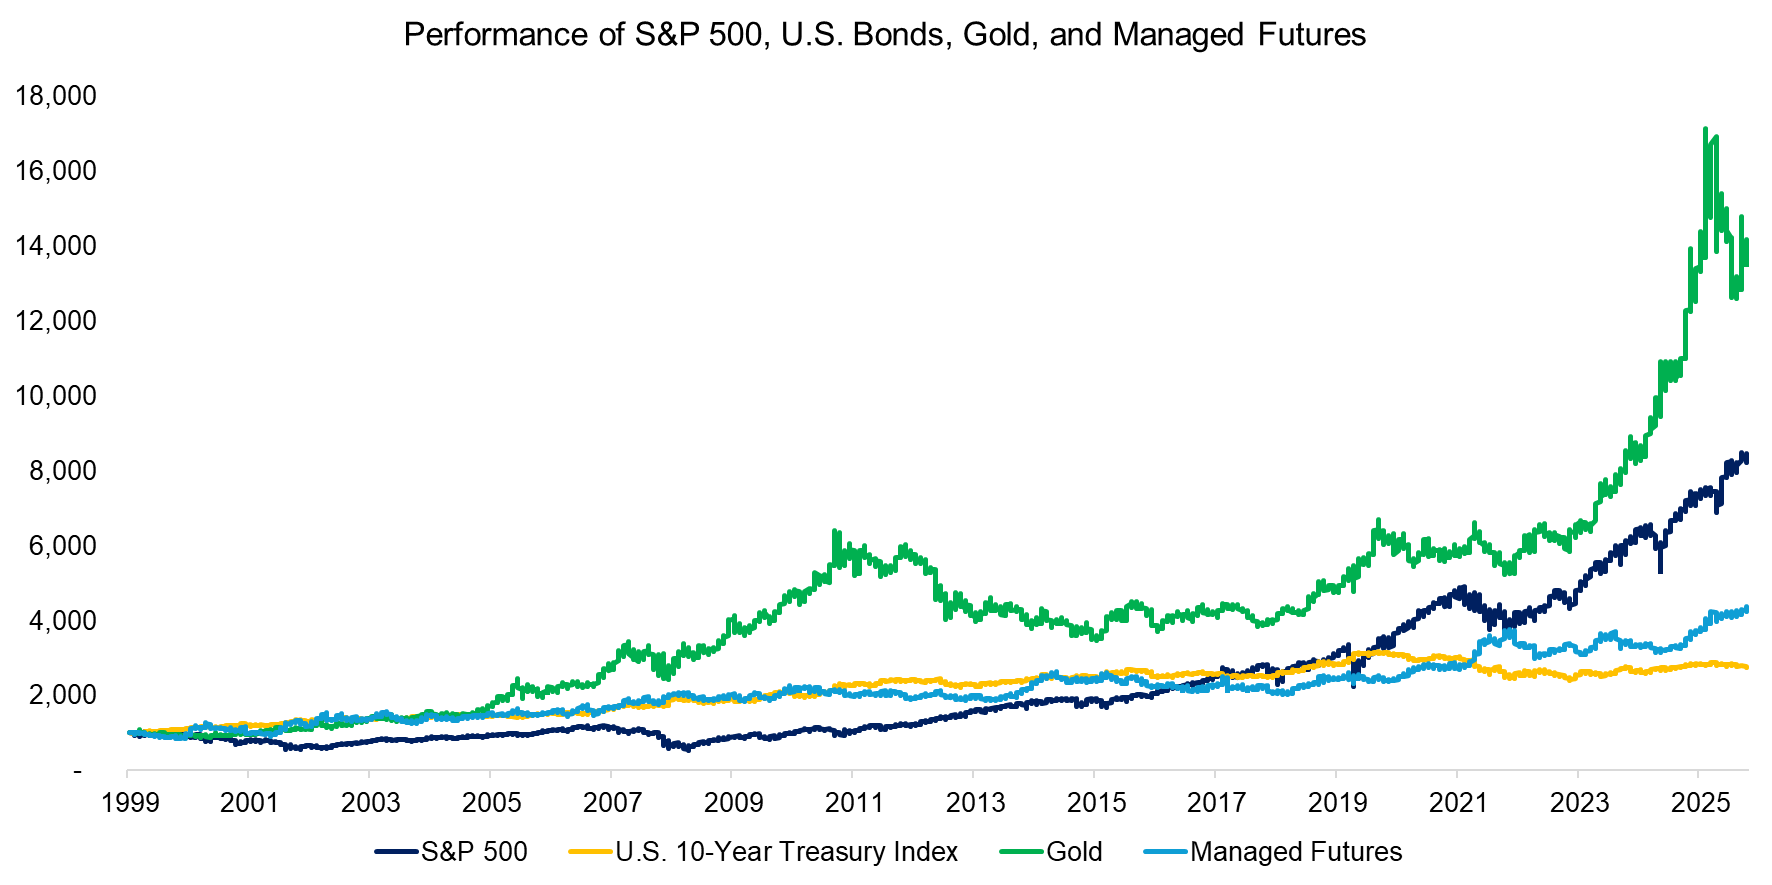
We use the SG Trend Index, which provides equal-weighted exposure to the 10 largest CTAs, from 2000 to 2019, and then the iMGP DBi Managed Futures Strategy ETF (DBMF) thereafter, which seeks to replicate this index’s returns. Low-cost ETFs are readily available for exposure to the U.S. 10-Year Treasury Bond and gold (read Bonds vs. Managed Futures: A 100-Year Perspective).
The 2000 starting point comes from the SG Trend Index’s inception and coincides with the implosion of the tech bubble. Over the last 25 years, gold performed best, and bonds performed worst.
Source: SG, Finominal
From a risk-adjusted perspective, U.S. bonds and gold generated the same Sharpe ratio of 0.59 between 2000 and 2026. Stocks and managed futures performed slightly worse, with both landing at a similar Sharpe ratio of 0.44. However, their volatility profiles differed markedly, with stocks the most volatile and bonds the least.
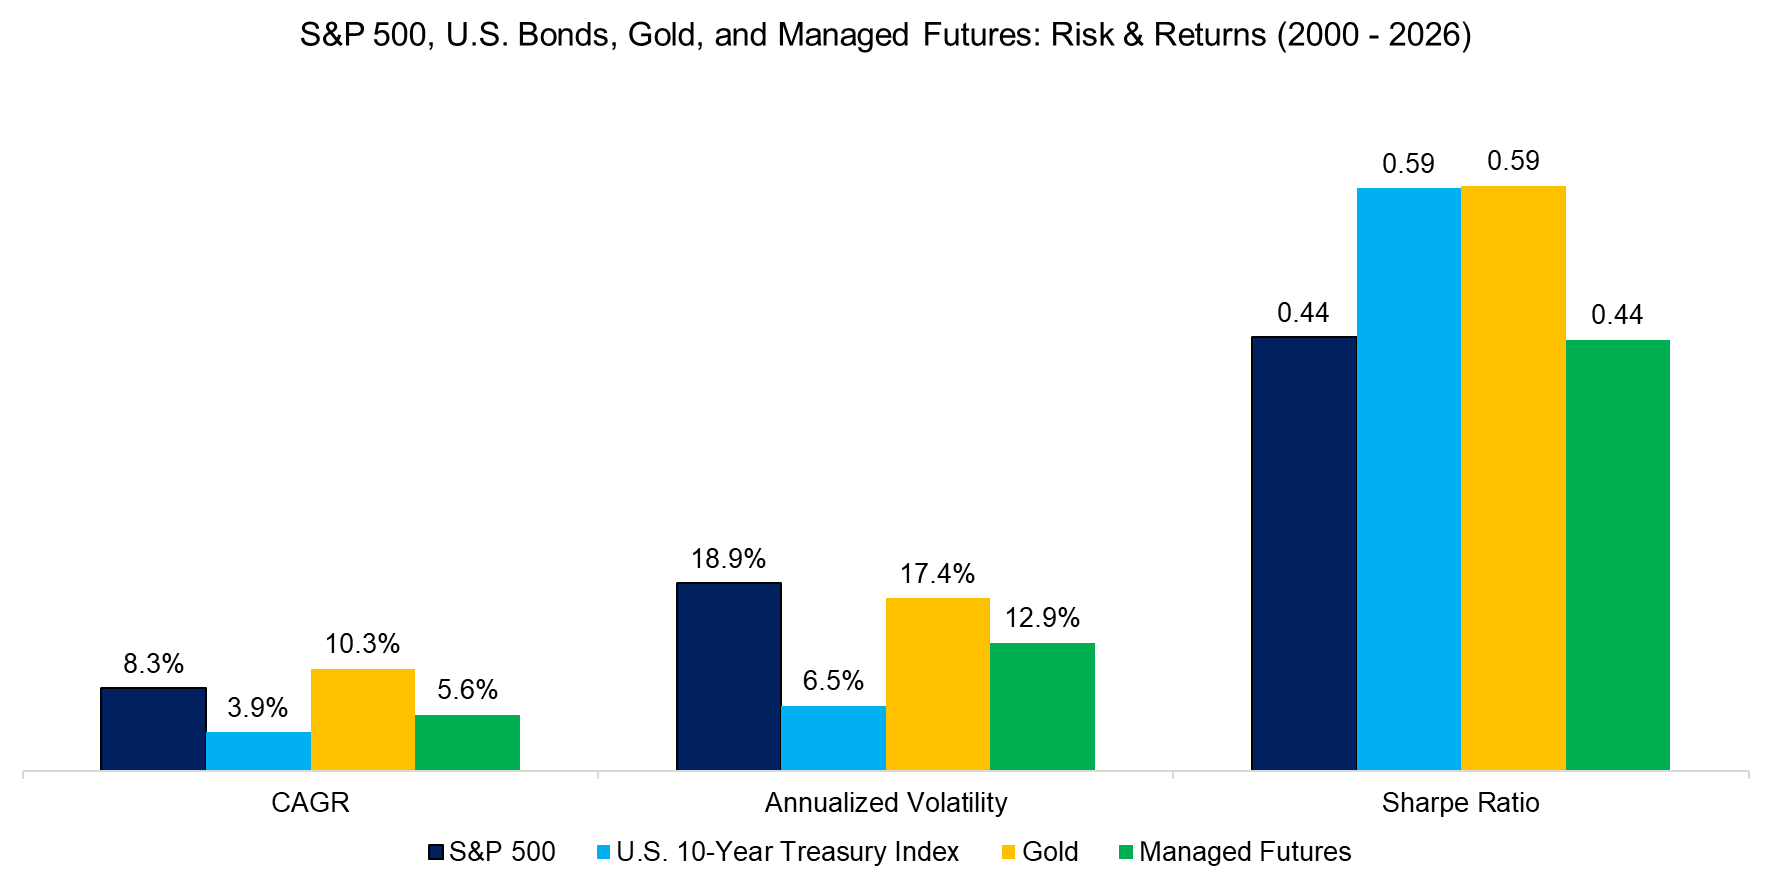
Source: SG, Finominal
DRAWDOWNS
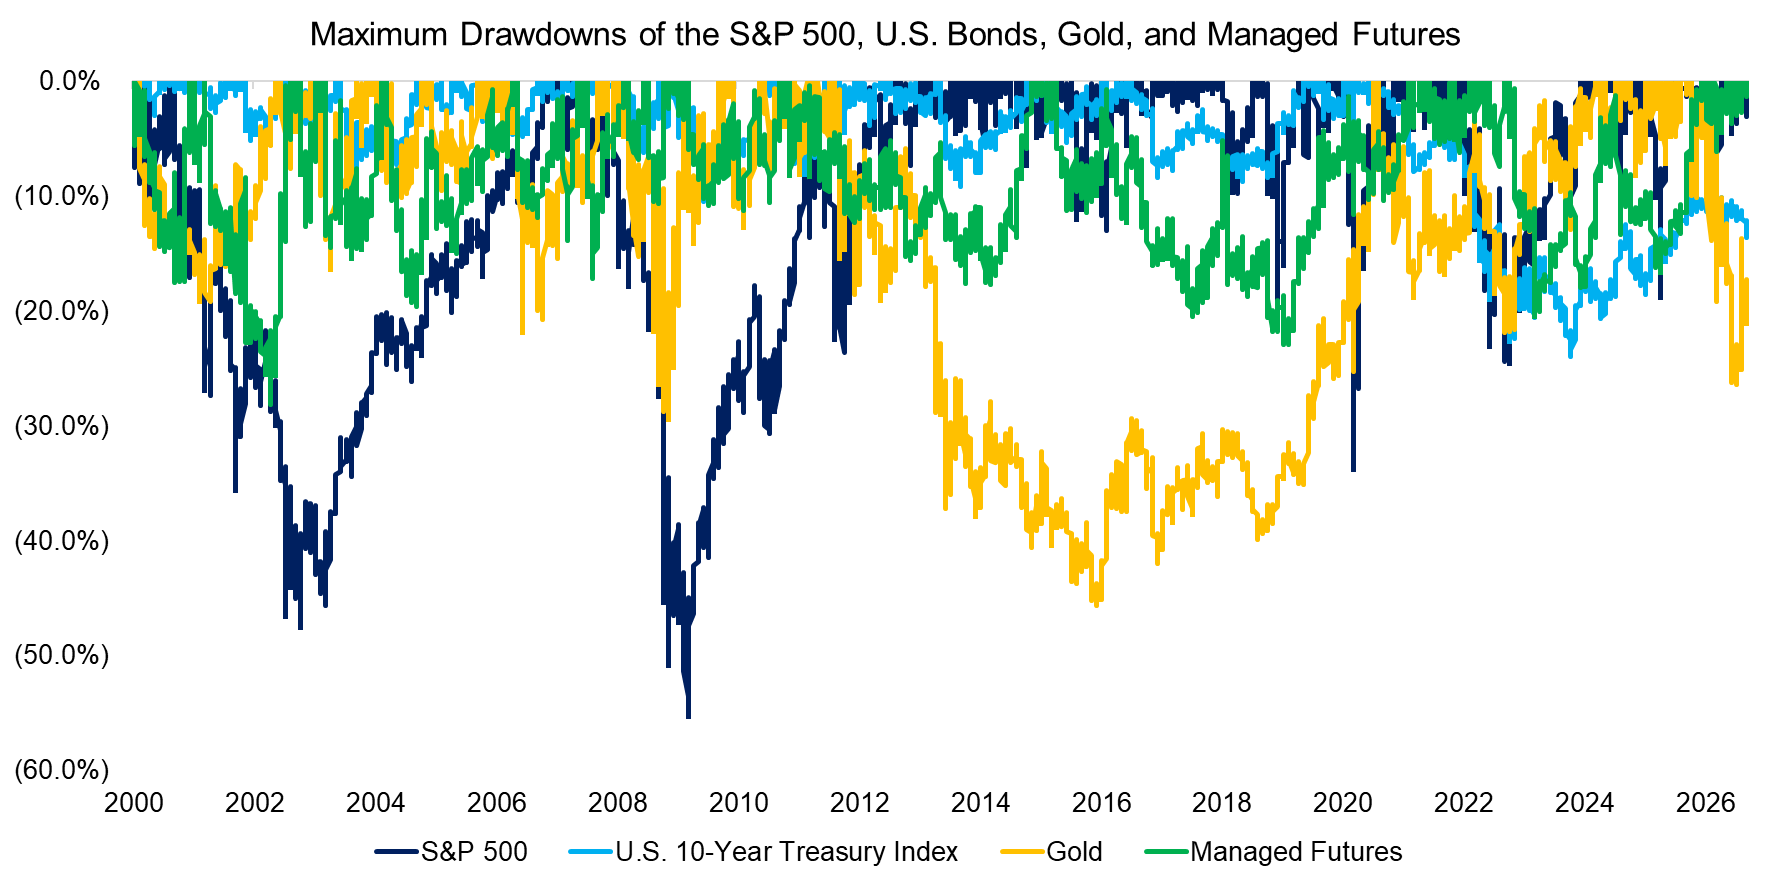
We show the rolling drawdowns of these four strategies and observe significant divergences. Most investors will recall the tech bubble implosion between 2001 and 2003 and the global recession in 2008, when the S&P 500 declined by 48% and 55%, respectively. Gold also fell 45% between 2011 and 2016, and U.S. bonds declined 24% between 2020 and 2024 (read How Much Can You Lose with Bonds?).
Source: SG, Finominal
CORRELATION ANALYSIS
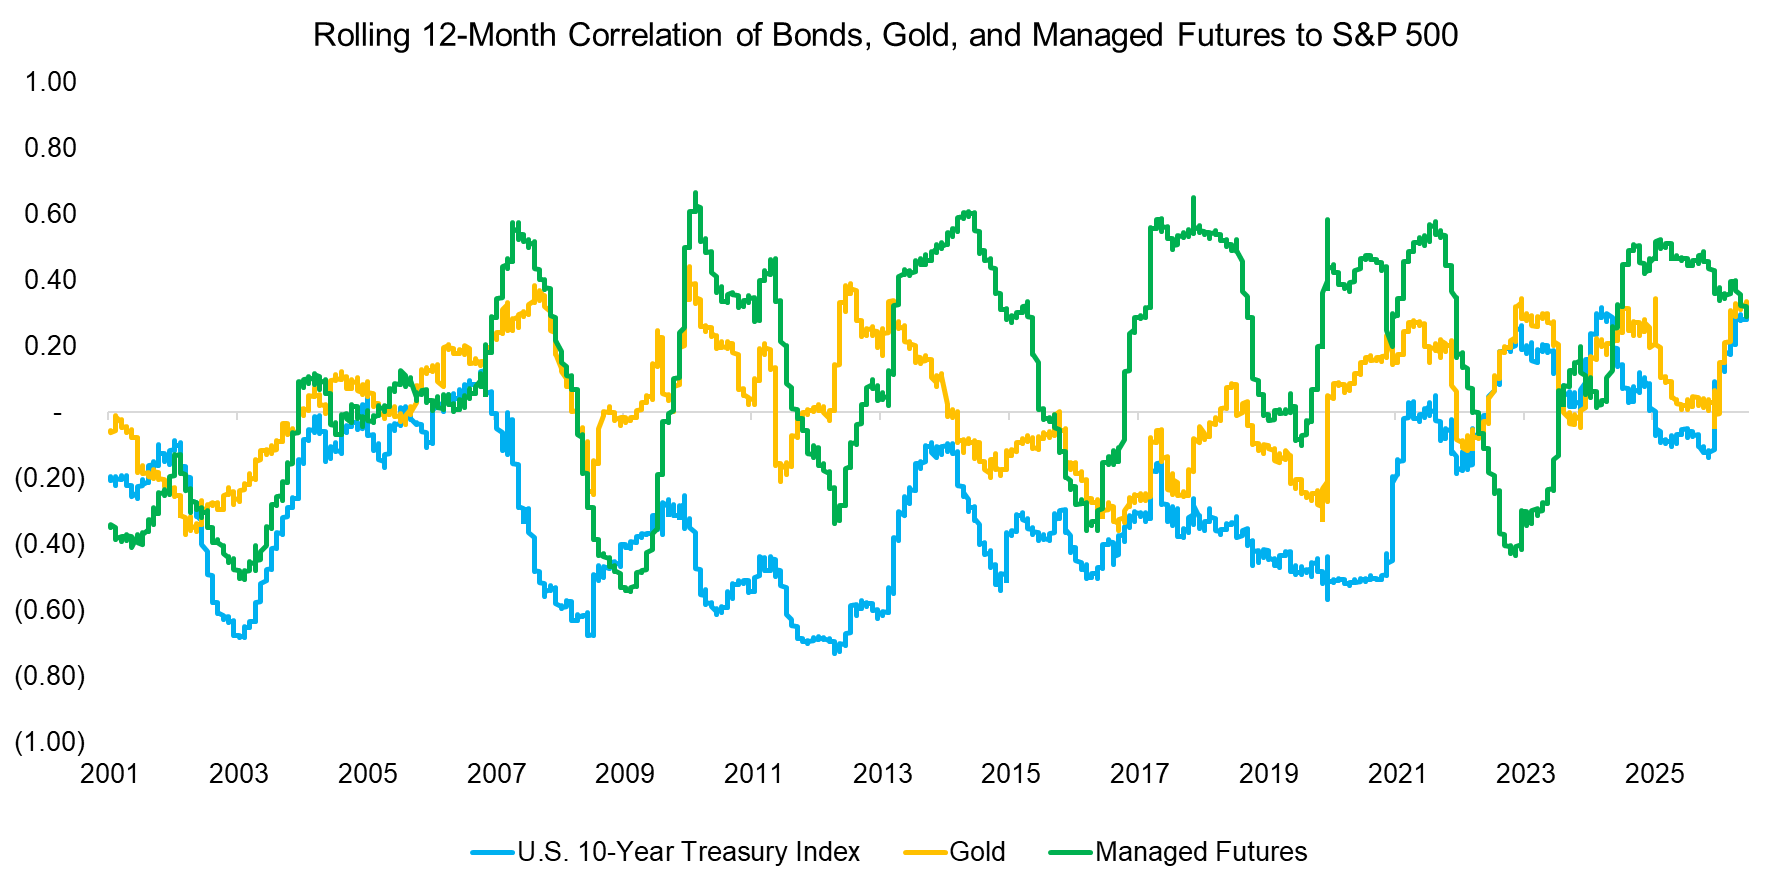
Next, we compute the average correlations of bonds, gold, and managed futures to the S&P 500. From 2000 to 2025, the average correlations ranged from -0.27 for U.S. bonds to 0.11 for managed futures. However, each has experienced periods of both positive and negative correlation to U.S. stocks.
Source: SG, Finominal
DIVERSIFICATION BENEFITS
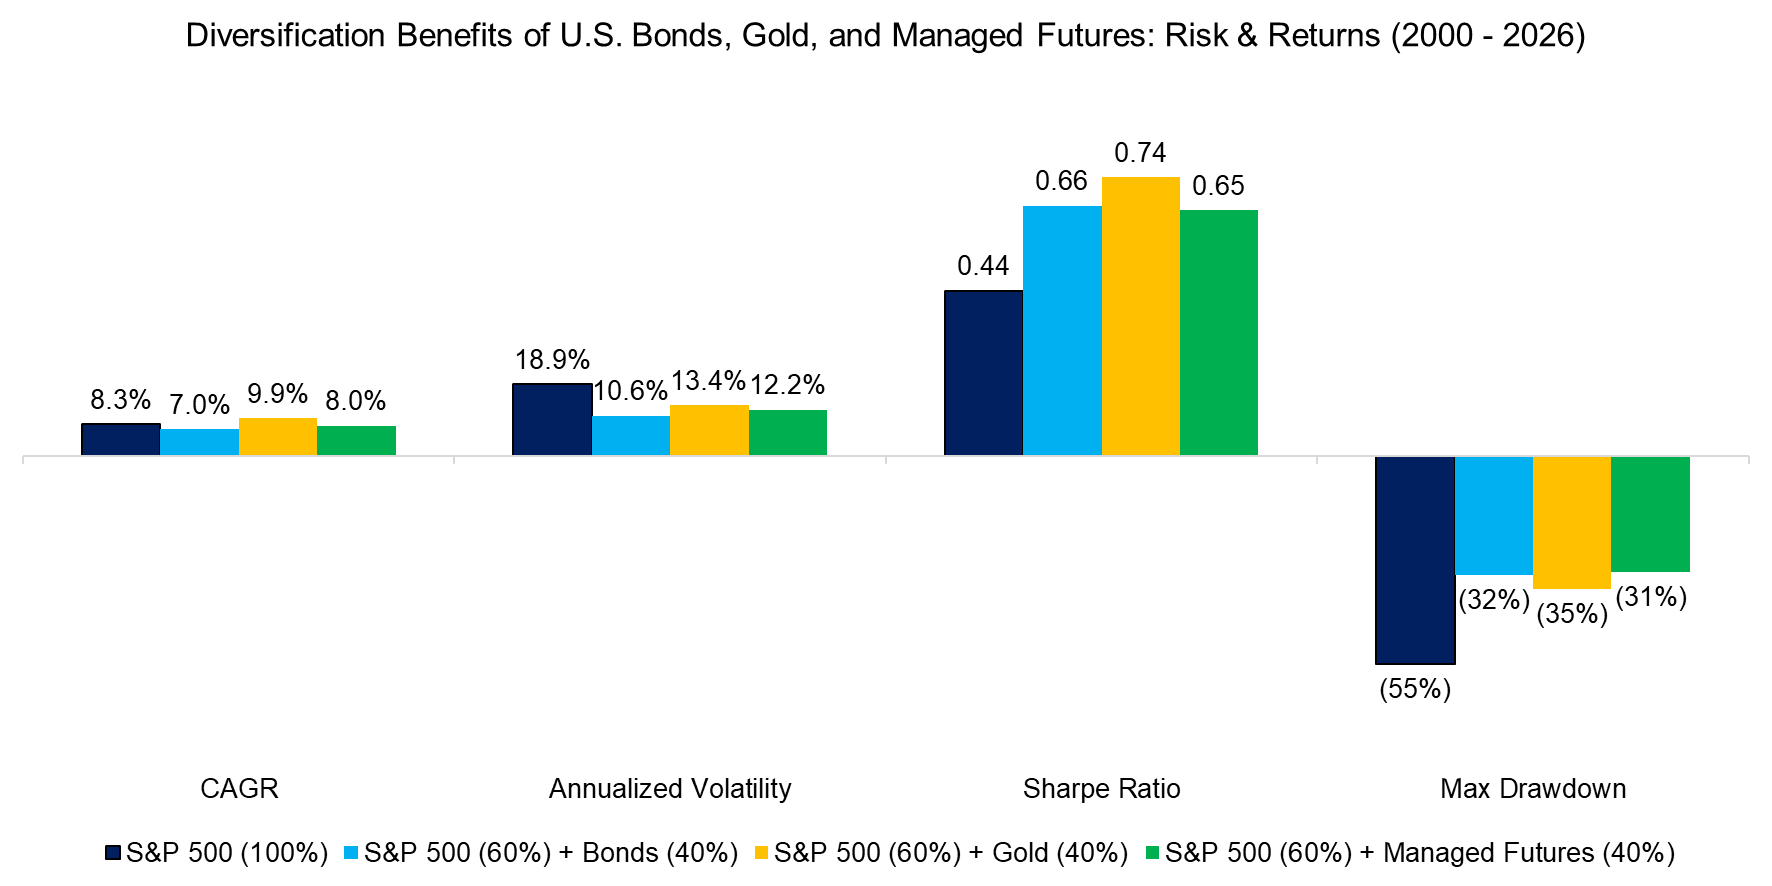
The low correlations to the U.S. stock market make all three strategies excellent diversifiers. We simulate adding a 40% allocation of each to a 100% equities portfolio over the last 25 years, which would have increased the Sharpe ratio in all three cases, assuming quarterly rebalancing and zero transaction costs. Gold generated the largest improvement in Sharpe ratio, from 0.44 to 0.74, which is unsurprising given its much higher standalone returns. Bonds and managed futures were tied at 0.66 and 0.65.
Source: SG, Finominal
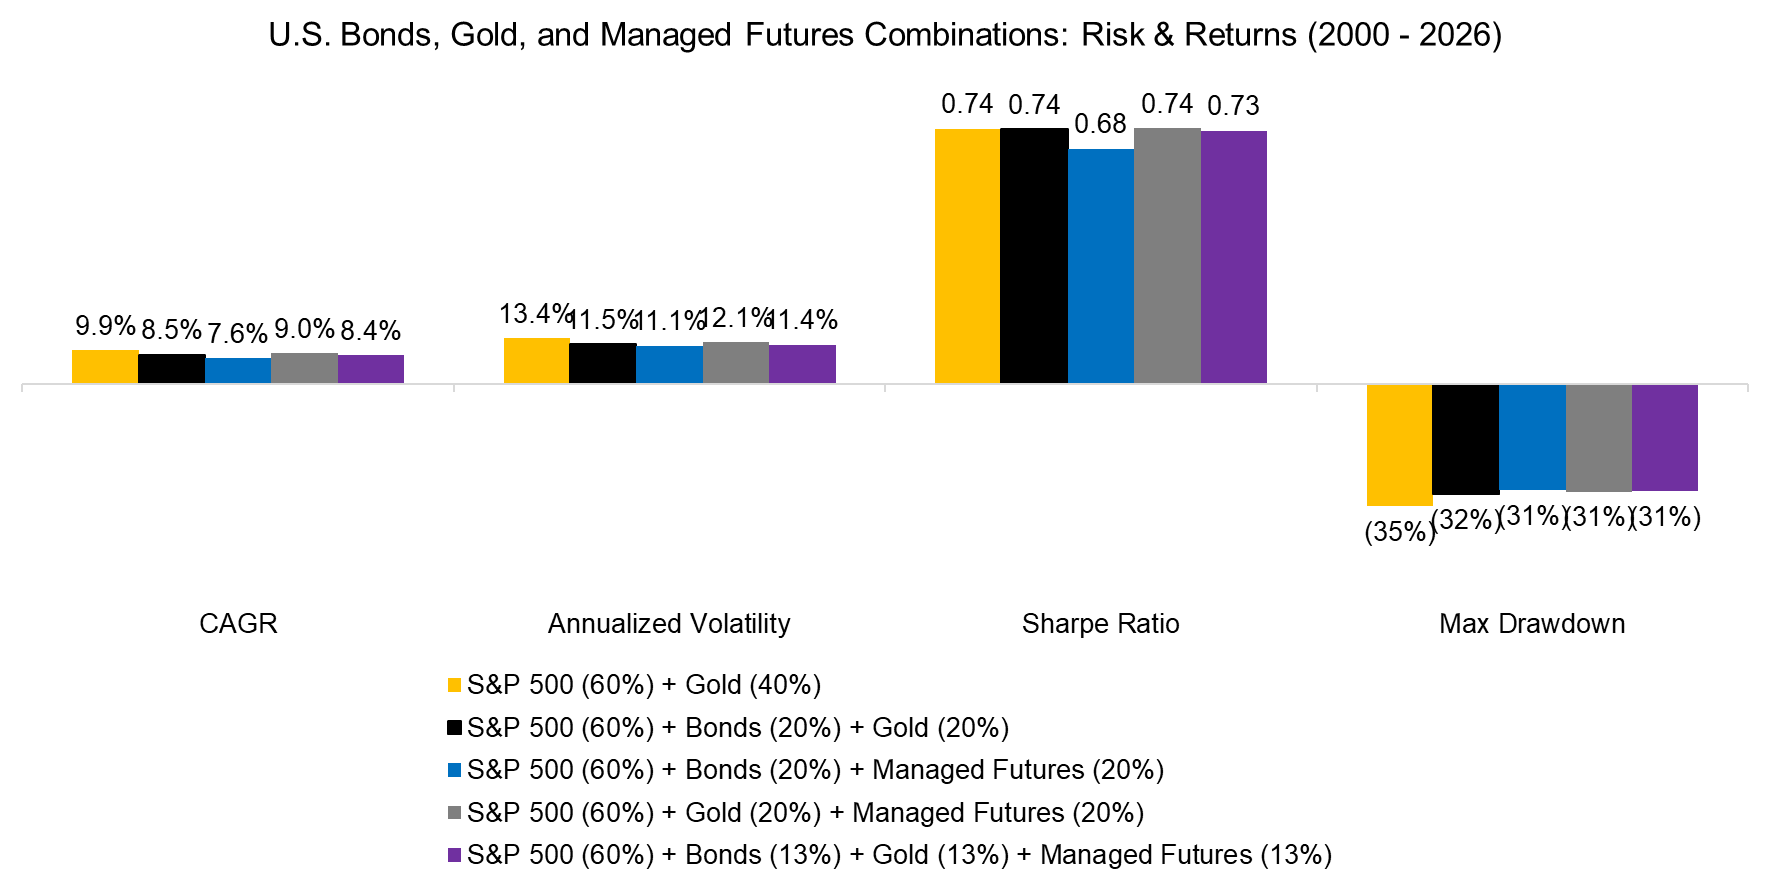
The correlation analysis also highlighted that the three strategies were only weakly correlated with each other. Bonds showed a 0.2 correlation with gold and zero correlation with managed futures over the last 25 years, compared to 0.20 between gold and managed futures.
These low correlations make it interesting to combine all three, which we simulate against the best single-strategy scenario: a 40% allocation to gold. We find that mixing gold equally with bonds or managed futures would have produced the same Sharpe ratio; only bonds plus managed futures would have been slightly worse.
Source: SG, Finominal
FURTHER THOUGHTS
As a follow-up to our previous analysis, using more realistic managed futures returns did not confirm their dominance versus bonds or gold. However, this analysis, like most financial research, is affected by timing luck – for example, gold performed strongly over the last 25 years.
That said, this analysis confirms that investors don’t need bonds for diversification: either gold or managed futures would have done equally well or better. This is naturally comforting, given that bonds are likely to become riskier going forward amid rising debt levels and declining populations.
RELATED RESEARCH
Bonds vs. Gold vs. Managed Futures: A 100-Year Perspective
Bonds vs. Managed Futures: A 100-Year Perspective
Managed Futures vs Factor Investing: A 100-Year Perspective
Diversifying vs De-Risking Funds
How Much Can You Lose with Bonds?
60/40 Portfolios Without Bonds
Bonds versus CTAs for Diversification
Gold & Silver: Buy-and-Hold vs Trend Following
How Much Should You Allocate to Managed Futures?
Combining Risk-Managed Equities and Managed Futures – II
Combining Risk-Managed Equities and Managed Futures
CTAs: With or Without Trend Following in Equities?
Carry versus Trend Following
Trend Following in Equities
Trend Following in Bear Markets
Replicating a CTA via Factor Exposures
Creating a CTA from Scratch – II
CTAs vs Global Macro Hedge Funds
Managed Futures: The Empire Strikes Back
Managed Futures: Fast & Furious vs Slow & Steady
Hedging via Managed Futures Liquid Alts
ABOUT THE AUTHOR
Nicolas Rabener is the CEO & Founder of Finominal, which empowers professional investors with data, technology, and research insights to improve their investment outcomes. Previously he created Jackdaw Capital, an award-winning quantitative hedge fund. Before that Nicolas worked at GIC and Citigroup in London and New York. Nicolas holds a Master of Finance from HHL Leipzig Graduate School of Management, is a CAIA charter holder, and enjoys endurance sports (Ironman & 100km Ultramarathon).
Connect with me on LinkedIn or X.