Factor Olympics Q3 2026
And the winner is…
SUMMARY
- The momentum factor leads, low volatility lags
- Similar returns between long-short and smart beta investing
- Except for value, where betting on cheap stocks has been unprofitable
INTRODUCTION
We present the performance of well-known global equity factors for the first nine months of 2026 and over the last decade. We also include the growth factor, which academic research shows has generated negative long-term returns but remains a widely followed investment style.
METHODOLOGY
We construct our global equity factors from long-short, beta-neutral portfolios of the top and bottom 20% of stocks. The universe of stocks comprises those making up 99% of the total market capitalization. Portfolios are created at the country level with monthly rebalancing, then aggregated into global factor indices using market-capitalization-weighted weights. Stocks are selected on the following metrics:
- Value: A combination of price-to-earnings and price-to-book multiples
- Size: Market capitalization
- Momentum: Total return over the last 12 months excluding the latest month
- Low volatility: Volatility over the last 12 months
- Profitability: Net income-over-equity
- Leverage: Debt-over-equity
- Growth: A combination of sales-per-share and earnings-per-share growth over the last three years
FACTOR OLYMPICS: EXCESS RETURNS
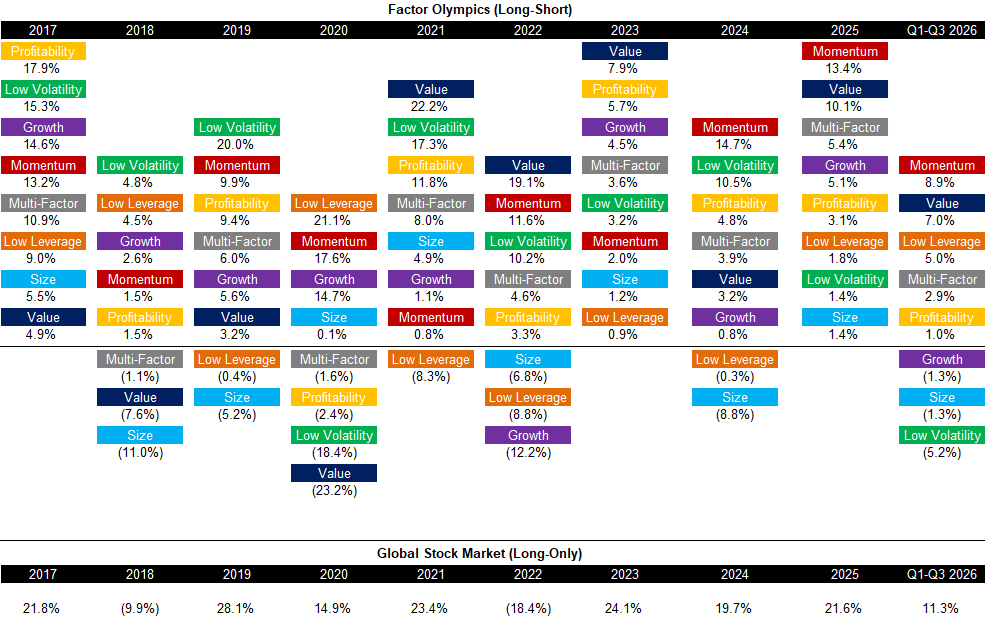
The table below ranks long-short performance of global equity factors for the first nine months of 2026 and over the past 10 years. Beyond showing performance, it illustrates the sharp year-to-year rotations in factor profitability, underscoring the value of diversifying across multiple factors.
Momentum was the top-performing factor, while low volatility ranked last. An equal-weighted portfolio of all factors, excluding growth, which academic research does not support, would have returned 2.9% before transaction, implementation, and management fees.
TRENDS IN FACTOR PERFORMANCE
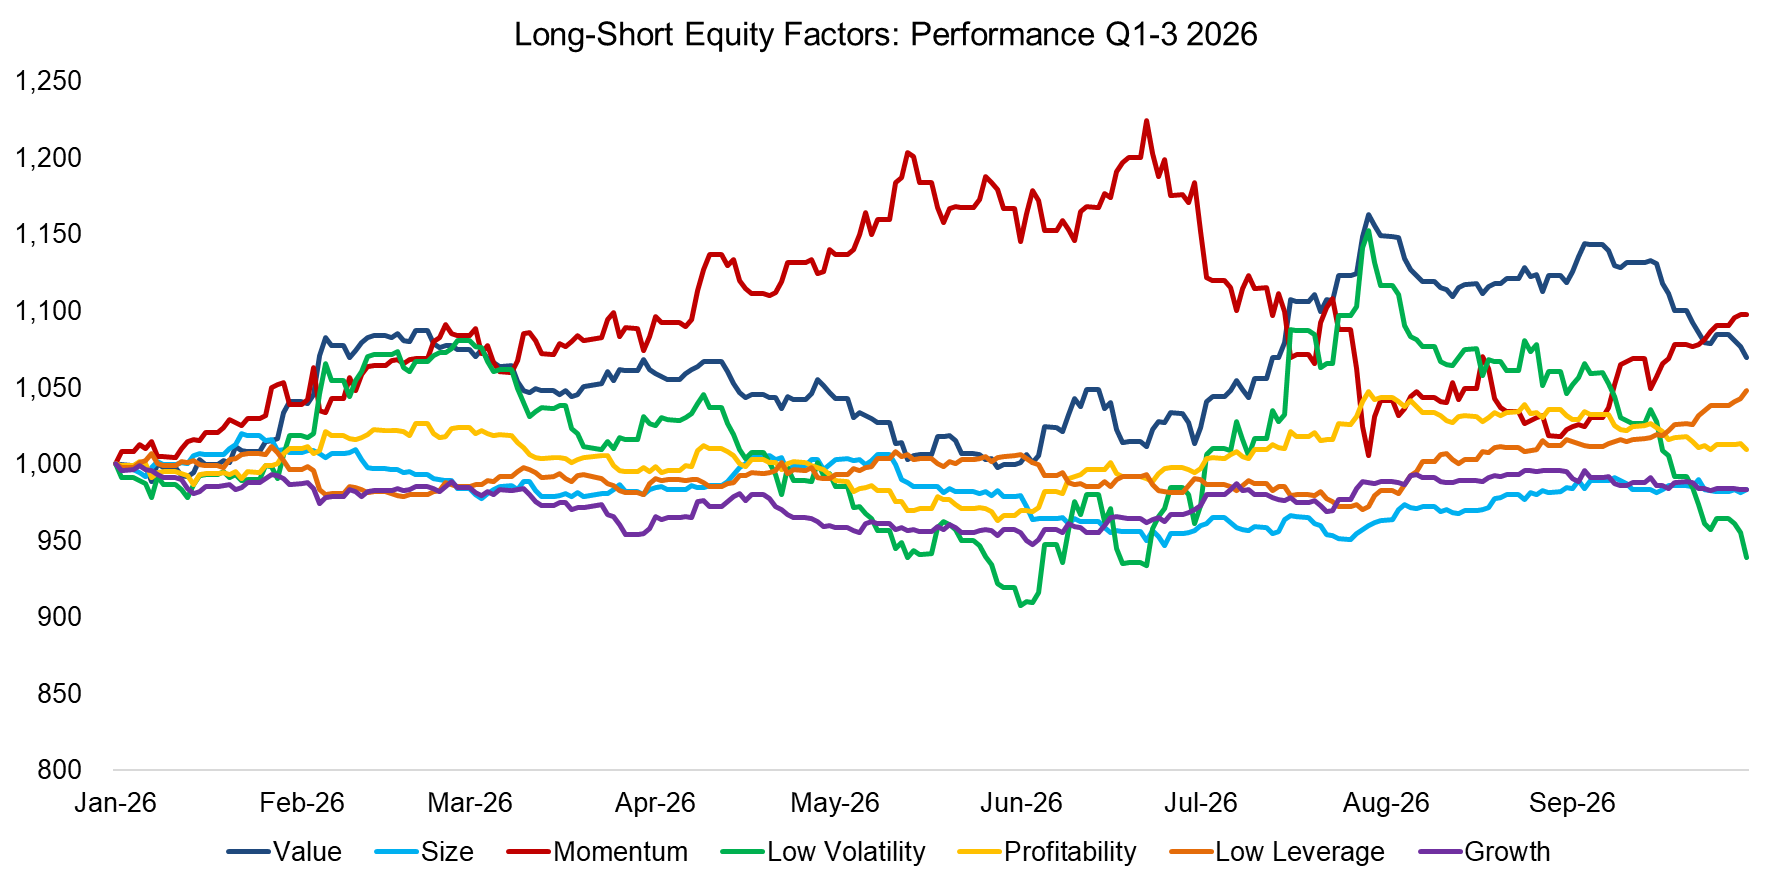
Q3 saw a pronounced factor rotation. Momentum gave back almost all of its year-to-date gain of nearly 20% before recovering in September. Value, by contrast, rallied strongly in July and August and held on to those gains. Low volatility went through a mini boom-and-bust.
Source: Finominal
FACTOR CORRELATIONS
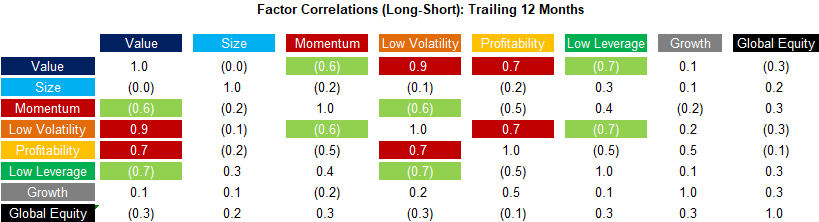
The 12-month correlation analysis reveals several strong positive relationships, including value & low volatility (0.9) and value & profitability (0.7). It also highlights notable negative correlations, such as value & momentum (-0.6), and value & low leverage (-0.7). Many of these relationships are structural rather than temporal – for example, cheap stocks often underperform and are frequently associated with high leverage.
Investors can naturally exploit advantageous correlations; e.g., buying cheap, low-volatility, but highly profitable companies seems like a sensible investing strategy.
Source: Finominal
PERFORMANCE OF LONG-SHORT MULTI-FACTOR PRODUCTS
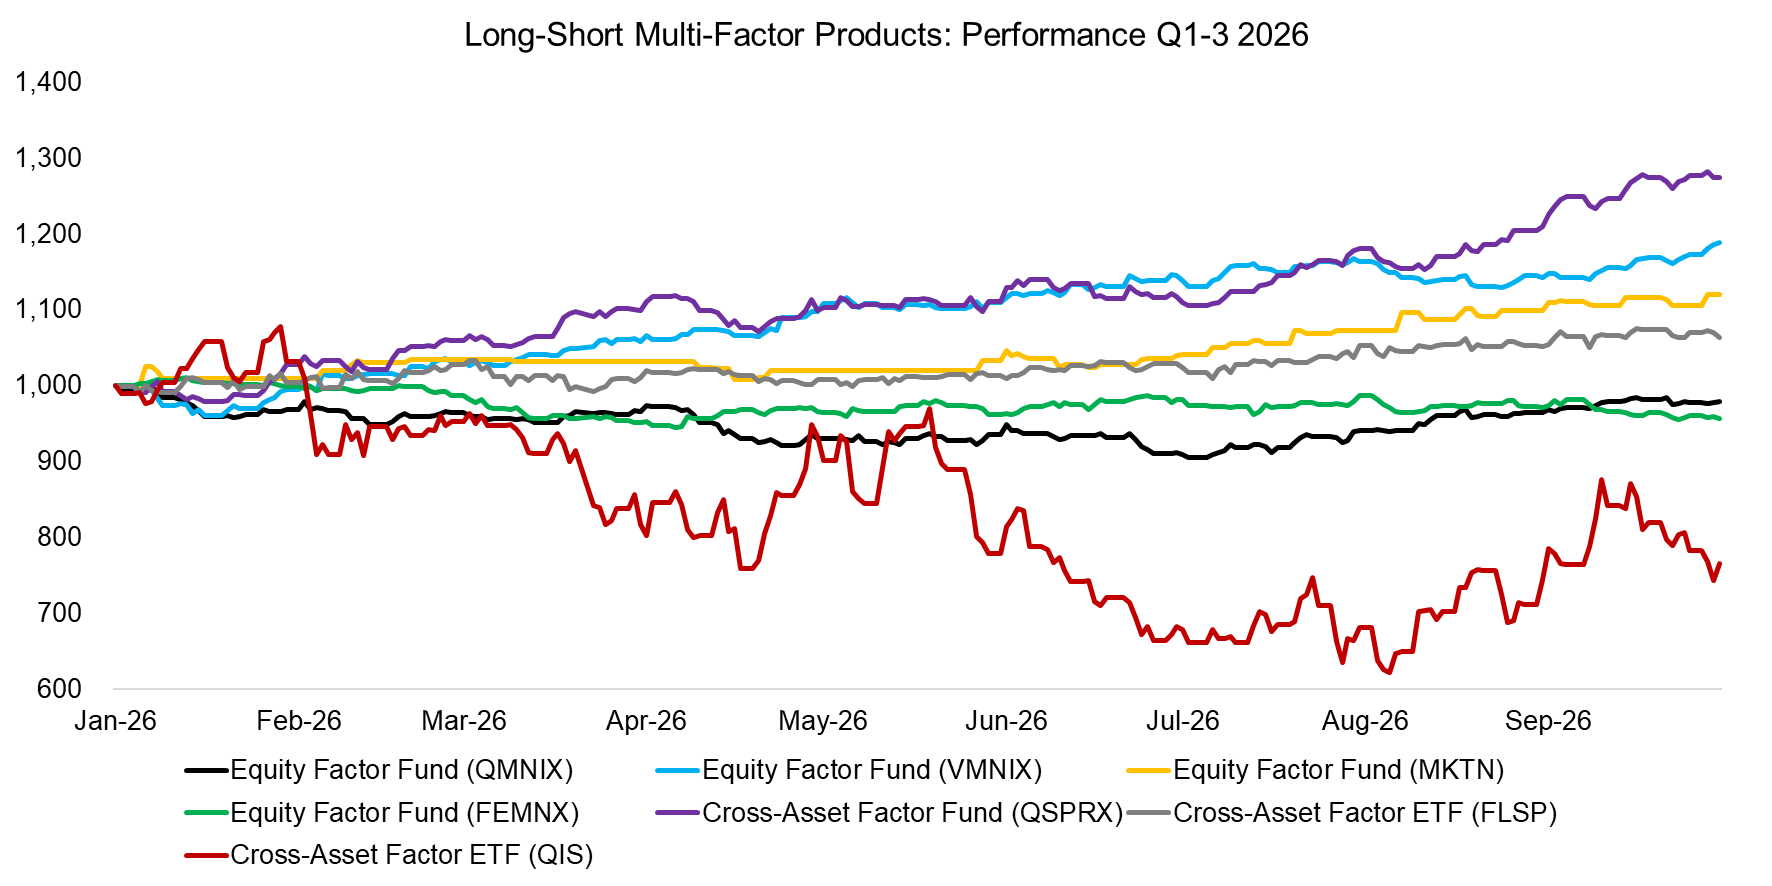
Only a handful of liquid alternative mutual funds and ETFs offer pure long-short factor exposure, as seen in academic research. There have been liquidations, such as Simplify’s Market Neutral Equity Long/Short ETF (EQLS) in 2025, but also new launches, such as Fidelity’s Equity Market Neutral Fund (FEMNX) and Federated Hermes MDT’s Market Neutral ETF (MKTN) in 2024 and 2025, respectively.
The best-performing fund in recent years, AQR’s Equity Market Neutral Fund (QMNIX), has not generated positive returns in 2026. In contrast, AQR’s cross-asset style premia fund (QSPRX) indicates that factor investing has been more profitable in fixed income, commodities, and currencies than in equities. Simplify’s Multi-QIS Alternative ETF (QIS) continued its exceptionally poor performance, and we would expect its liquidation soon.
LONG-SHORT VS LONG-ONLY EXCESS RETURNS
Although investors should allocate to factors constructed as long-short portfolios, which offer strong diversification benefits, most invest via long-only smart beta ETFs (read Smart Beta vs Alpha + Beta). Given this, we compute the excess returns for the long-only portfolios of the equity factors (read Market-Neutral versus Smart Beta Factor Investing).
Comparing these with the long-short factor returns shows broadly similar results for both approaches, except for value. The long-short value factor returned a strong 7.0%, whereas cheap stocks underperformed the global stock market by 0.3%. Part of this gap reflects portfolio construction: the stocks in the long-short portfolios are equal-weighted, while the stocks in the long-only portfolios are market-cap-weighted. The other explanation is that shorting expensive stocks has been profitable (read Long-Short vs Long-Only Factor Investing).
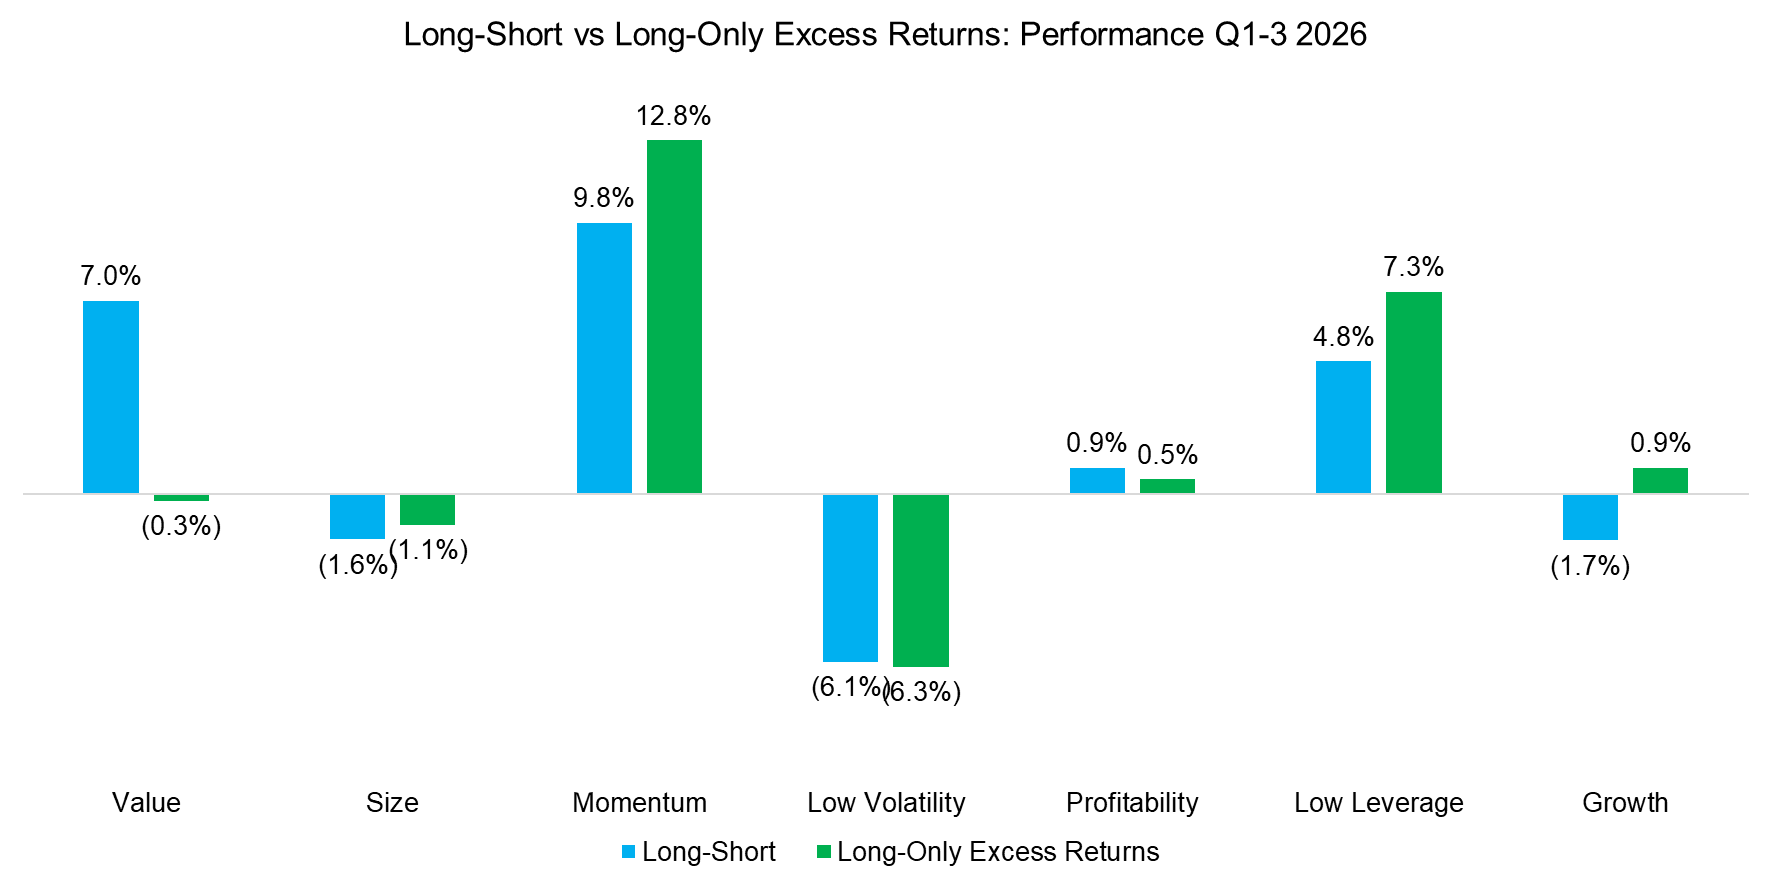
Source: Finominal
FURTHER THOUGHTS
The strong performance of managed futures funds has triggered a wave of ETF launches, from large asset managers like Fidelity, Invesco, iShares, and Virtus to boutiques like Simplify and Unlimited.
Curiously, market-neutral multi-factor strategies have seen no similar wave, even though funds like AQR’s QMNIX and Vanguard’s VMNIX are trading close to their all-time highs. These strategies deliver exactly what investors should want: positive, uncorrelated returns backed by solid academic research. They have done their job, so what are investors and asset managers waiting for?
Market-Neutral versus Smart Beta Factor Investing
Long-Short vs Long-Only Factor Investing
Factor Optimization via ETFs
Smart Beta ETF vs Customized Factor Portfolios
Factor Exposure Analysis 114: Factor Offsetting
Improving Smart Beta Attribution Analysis II
Quality in Small versus Large-Cap Stocks
The Illusion of the Small-Cap Premium
Shorting Lousy Stocks = Lousy Returns?
Higher Volatility, Higher Alpha?
Outperformance Ain’t Alpha
Improving the Odds of Value Investing
The Value Factor’s Pain: Are Intangibles to Blame?
Smart Beta vs Alpha + Beta
How Painful Can Factor Investing Get?
GARP Investing: Golden or Garbage? II
Are Low-Risk Stocks Really Low-Risk?
ABOUT THE AUTHOR
Nicolas Rabener is the CEO & Founder of Finominal, which empowers professional investors with data, technology, and research insights to improve their investment outcomes. Previously he created Jackdaw Capital, an award-winning quantitative hedge fund. Before that Nicolas worked at GIC and Citigroup in London and New York. Nicolas holds a Master of Finance from HHL Leipzig Graduate School of Management, is a CAIA charter holder, and enjoys endurance sports (Ironman & 100km Ultramarathon).
Connect with me on LinkedIn or X.